Example of a completed D81 form
A made-up couple, to show how the tables on the D81 form fit together. It covers questions 8 to 11, 15, 17 and 19; the others hold your own details and your own words (see the D81 guide for each question). It isn't a model answer and says nothing about what's fair. Questions 13 and 14 are yours to write.
The made-up couple
The applicant and respondent married in 2012, separated in November 2025 and have two children, who will live with the applicant. They agreed a settlement through out-of-court dispute resolution.
Before the order: they own their home jointly, 50/50. The applicant has £8,000 of savings, an £85,000 workplace pension, a £1,340 credit card and earns £3,050 a month after tax. The respondent has a £14,000 ISA, a £140,000 pension, a £6,000 car loan and earns £34,000 a year after tax. There is a joint current account of £2,450 and a £3,000 Junior ISA for one of the children.
In return for the applicant keeping the home, the respondent receives the joint account, a lump sum and part of the applicant's pension. Under their made-up agreement:
- the jointly owned home (worth £450,000, with a £210,000 mortgage) goes to the applicant, who keeps the mortgage
- the joint current account goes to the respondent
- the applicant pays the respondent a lump sum of £8,000
- half of the applicant's £85,000 pension (£42,500) is shared to the respondent
- child maintenance paid by the respondent rises from £400 to £600 a month
Question 8: capital now
The tables scroll sideways on a phone.
| Line | Applicant | Respondent | Child(ren) |
|---|---|---|---|
| Property 1, after mortgage (joint, 50/50) | £120,000 | £120,000 | £0 |
| Other capital | £9,225 | £15,225 | £3,000 |
| Gross capital total | £129,225 | £135,225 | £3,000 |
| Liabilities | £1,340 | £6,000 | £0 |
| Net capital total | £127,885 | £129,225 | £3,000 |
| Pensions (cash equivalent) | £85,000 | £140,000 | £0 |
| PPF compensation | £0 | £0 | £0 |
| Total capital and pensions | £212,885 | £269,225 | £3,000 |
Other capital: the joint account (£2,450) is split in half; the applicant has £8,000 of savings, the respondent a £14,000 ISA, and there's a £3,000 Junior ISA for one of the children.
Question 10: capital after the order
| Line | Applicant | Respondent | Child(ren) |
|---|---|---|---|
| Property 1, after mortgage | £240,000 | £0 | £0 |
| Other capital | £0 | £24,450 | £3,000 |
| Gross capital total | £240,000 | £24,450 | £3,000 |
| Liabilities | £1,340 | £6,000 | £0 |
| Net capital total | £238,660 | £18,450 | £3,000 |
| Pensions (cash equivalent) | £42,500 | £182,500 | £0 |
| PPF compensation | £0 | £0 | £0 |
| Total capital and pensions | £281,160 | £200,950 | £3,000 |
The check: everyone's combined total is £485,110 in both tables. Nothing has gone missing. The applicant's other capital falls to £0 because the £8,000 savings pay the lump sum, which appears in the respondent's other capital with the whole joint account.
Questions 9 and 11: net monthly income
| Line | Applicant now | Respondent now | Applicant after | Respondent after |
|---|---|---|---|---|
| A. Earned income | £3,050 | £2,833 | £3,050 | £2,833 |
| B. State benefits (Child Benefit) | £195 | £0 | £195 | £0 |
| F. Sub-total | £3,245 | £2,833 | £3,245 | £2,833 |
| G. Child support paid between you | £400 | -£400 | £600 | -£600 |
| I. Sub-total | £400 | -£400 | £600 | -£600 |
| M. Grand total | £3,645 | £2,433 | £3,845 | £2,233 |
The respondent's £34,000 a year net pay is £2,833 a month. Child Benefit for two children, £179.80 every 4 weeks at the GOV.UK rates when we checked, is £195 a month (13 payments a year). Lines C to E, H and J to L are £0 in this example. Line G mirrors: a plus for the one who receives it, a minus for the one who pays.
Where everyone will live, and the notices
Question 15: the applicant and children will live at the home (owner); the respondent in a rented flat (tenant).
Question 17: because the home is transferred, the mortgage provider was served on 20 August 2026. Its 14 days to file a statement in answer, beginning with the day of service, ended on 2 September 2026 (FPR 9.13(5)).
Question 19: because there's a pension sharing order, the pension scheme was served on the same day.
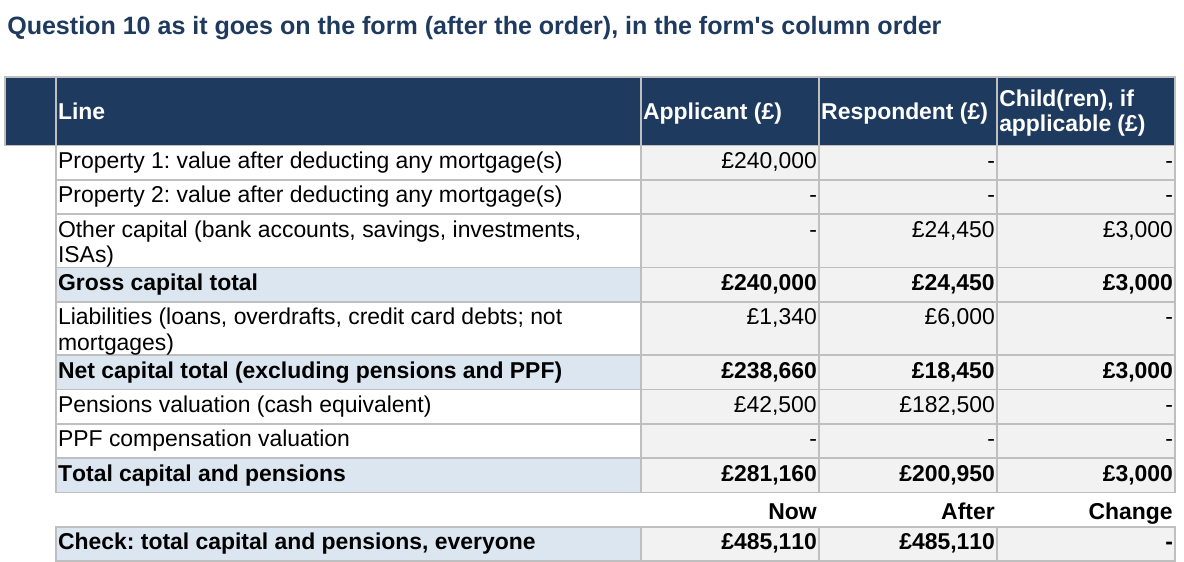
The D81 Organiser builds questions 8 to 11 from one list of what you own and owe, in the form's column order, and checks the totals add up.
Sources
Free help: GOV.UK, Advicenow, or a solicitor or family mediator for advice about your own case.